Most people associate estate planning with one document: a will.
A will is certainly an important estate planning document. It can determine who receives certain property after your death, nominate a personal representative to administer your estate, and identify guardians for minor children.
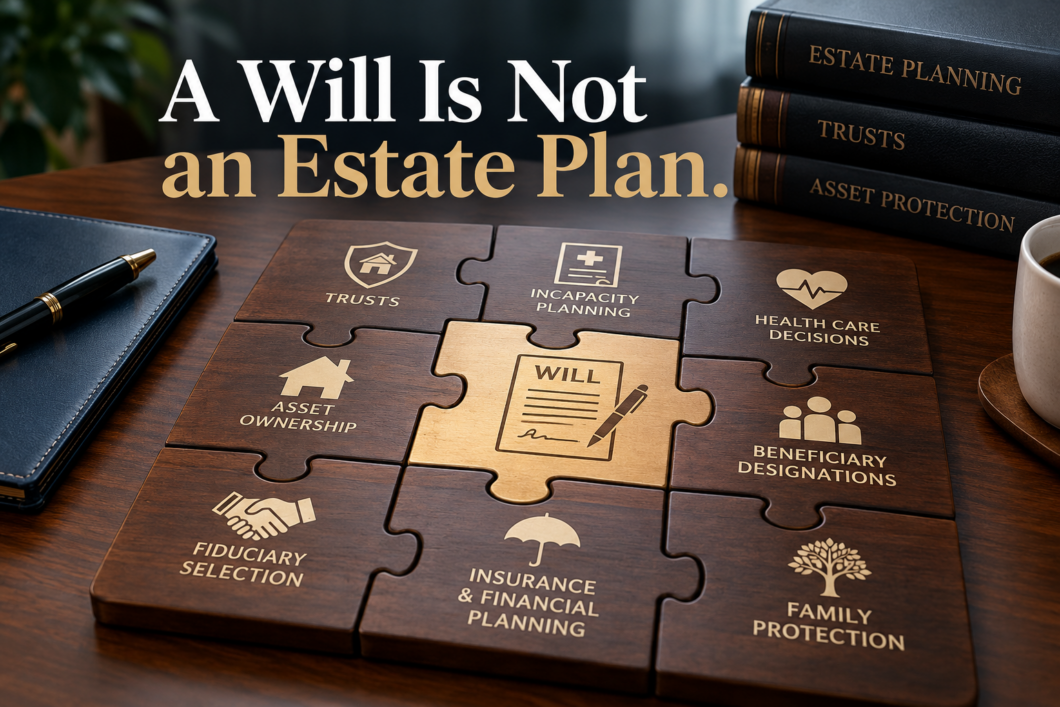
But having a will does not necessarily mean you have a complete estate plan.
A well-designed estate plan looks beyond what happens after death. It considers what happens if you become incapacitated, how your assets are owned, who can make financial and medical decisions for you, how beneficiary designations coordinate with your other documents, whether probate can or should be avoided, and how an inheritance should be managed for the people you care about.
The goal isn’t simply to have documents. The goal is to have a coordinated plan that works when you and your family need it.
1. Your Will: An Important Starting Point
A Last Will and Testament provides instructions for administering assets that become part of your probate estate.
Among other things, a properly prepared Florida will can:
- identify the beneficiaries of your probate estate;
- nominate the person you want to serve as your personal representative;
- nominate guardians for minor children; and
- create trusts or other provisions for beneficiaries when appropriate.
But a will has important limitations.
A will generally does not control assets that pass outside probate through joint ownership, beneficiary designations, rights of survivorship, or certain trust arrangements. And because a will generally operates at death, it does little to address one of the most important estate-planning risks during your lifetime: incapacity.
That is why a will should usually be viewed as one component of a broader estate plan.
2. Incapacity Planning: Who Can Act for You?
Estate planning isn’t only about death.
An accident, illness, or cognitive decline can leave someone temporarily or permanently unable to handle financial or medical decisions.
A complete estate plan should therefore consider documents such as a:
Durable Power of Attorney. This allows a trusted person to handle authorized financial and legal matters on your behalf.
Designation of Health Care Surrogate. This identifies the person or persons you want making health care decisions if you cannot make them yourself.
Living Will. This provides instructions concerning end-of-life medical treatment under the circumstances provided by Florida law.
Appropriate health care and privacy authorizations may also help the people you trust obtain medical information when necessary.
Without proper incapacity planning, family members may encounter unnecessary obstacles—and in some circumstances may need to seek court involvement to obtain authority to act for you.
3. A Revocable Trust: When It Makes Sense
Not everyone needs a revocable living trust. For the right person or family, however, a trust can become the centerpiece of the estate plan.
A properly designed and funded revocable living trust can provide for management of trust assets during incapacity and establish how those assets will be administered after death. It may also help avoid probate for assets properly transferred to the trust.
Trust planning can be particularly valuable when there are additional considerations, such as:
- minor children;
- beneficiaries who should not receive a substantial inheritance outright;
- blended families;
- beneficiaries with special needs;
- real estate in multiple jurisdictions; or
- a desire to provide longer-term protection and management of inherited assets.
The important word, however, is funded.
Creating an excellent trust document but failing to coordinate ownership of assets with the trust can undermine the very objectives the trust was intended to accomplish.
4. How Your Assets Are Titled Matters
Estate planning is not simply document drafting.
Consider a house, bank account, brokerage account, or business interest. How that asset is legally owned can determine what happens to it when an owner dies.
An asset may be owned individually, jointly, with survivorship rights, through an LLC or corporation, or in a trust. Real estate may also be subject to particular deed arrangements.
Each form of ownership can have different consequences.
This is one reason an estate plan should include a review of significant assets and their ownership rather than simply producing a stack of legal documents.
5. Beneficiary Designations Can Override Your Will
This is one of the most frequently misunderstood aspects of estate planning.
Many valuable assets transfer according to beneficiary designations, rather than under a will.
These may include:
- retirement accounts;
- life insurance policies;
- annuities; and
- certain payable-on-death or transfer-on-death accounts.
For example, changing your will generally does not change the beneficiary designation on your retirement account.
That can create unintended results when someone updates estate-planning documents after a marriage, divorce, birth, death, or other significant event but fails to review beneficiary designations.
A coordinated estate plan therefore considers not only what your documents say, but also how your assets will actually transfer.
6. Choosing the Right People Is as Important as Choosing the Right Documents
Estate planning requires a series of very human decisions.
Who should manage your finances if you cannot?
Who should make medical decisions for you?
Who should administer your estate?
Who should serve as trustee?
Who should care for your minor children?
These roles require different abilities. The person you trust most emotionally may not necessarily be the best person to manage investments, administer a trust, or navigate complex family dynamics.
A thoughtful estate plan considers not only whom you trust, but which person is best suited for each particular responsibility.
7. Protecting the People Who Inherit From You
Estate planning is also about what happens after an inheritance reaches the next generation.
Leaving everything outright may be perfectly appropriate in some families. In others, it may expose an inheritance to risks that could have been addressed through planning.
Depending on the circumstances, a trust may allow an inheritance to be managed for a beneficiary while addressing concerns involving:
- age or financial maturity;
- creditors;
- divorce;
- disability or special needs;
- substance abuse or other vulnerabilities; or
- long-term family wealth preservation.
The appropriate structure depends heavily on the beneficiary and the family’s objectives. There is no single distribution formula that works for everyone.
8. Insurance and Financial Planning Are Part of the Conversation
Legal documents cannot solve every estate-planning problem.
Life insurance, retirement planning, liquidity, business succession, investment planning, and tax considerations may all affect whether an estate plan actually accomplishes its objectives.
This is why effective estate planning often involves coordination among the client’s attorney, financial advisor, accountant, insurance professional, and other advisors.
The legal documents should support the broader financial plan—not exist independently from it.
9. An Estate Plan Is Not “One and Done”
Even a carefully designed estate plan can become outdated.
Consider reviewing your plan following significant events such as:
- marriage or divorce;
- the birth or adoption of a child or grandchild;
- the death or incapacity of a beneficiary or fiduciary;
- a significant change in assets;
- the purchase or sale of real estate;
- starting or selling a business;
- moving to another state; or
- significant changes in tax or estate-planning laws.
Even without a major life event, periodically reviewing your plan can identify outdated beneficiary designations, fiduciaries who are no longer appropriate, assets that were never properly coordinated with a trust, or provisions that no longer reflect your wishes.
Do You Have an Estate Plan—or Just a Will?
Having a will is an important step. But the more important question is whether all the pieces of your estate plan actually work together.
Ask yourself:
If I became incapacitated tomorrow, would the right people have the legal authority to manage my finances and make health care decisions for me?
If I died tomorrow, would my assets actually pass the way I intend?
Are my beneficiary designations and account titles consistent with my estate-planning documents?
Have I chosen the right people to administer my estate, manage any trusts, and make decisions for me if necessary?
Have I considered how an inheritance should be received and managed by my beneficiaries?
For some people, the appropriate plan may be relatively straightforward: a will, incapacity documents, appropriate beneficiary designations, and careful asset titling.
For others, a revocable trust and more sophisticated planning may be appropriate.
The objective is not complexity for its own sake. It is to identify your needs and build a coordinated plan around them.
Final Thoughts
A will is important. But a will is not an estate plan.
A complete estate plan coordinates your legal documents, asset ownership, beneficiary designations, incapacity planning, fiduciary choices, and financial planning so they work together.
Ultimately, estate planning is less about the documents themselves than what those documents are intended to accomplish: protecting you during your lifetime, providing clear instructions when you cannot speak for yourself, and creating an orderly plan for the people and causes you care about.
How Gonzalez Law Can Help
At Gonzalez Law, we help individuals and families develop estate plans designed around their particular circumstances, assets, family relationships, and long-term objectives.
Whether you need to create your first estate plan or review documents prepared years ago, we can help you determine whether your existing plan still reflects your wishes—and whether all of its pieces actually work together.
Protecting your business, your assets, and your family’s future.